
Nigeria is one of the largest remittance destinations in the world, and the people sending money from the UK and the US are usually paying school fees, supporting family or putting money towards property. Finding a way to send is easy: apps, banks and transfer companies all compete for it. The harder questions are what actually lands in Nigeria, in which currency, under which rules, and what you can do if a transfer goes wrong. This guide answers those for senders in the UK and the US, using the Central Bank of Nigeria’s own documents and the sender-side rules in each country.
This is general information, not financial, tax or legal advice. We do not rank providers or recommend one, and nothing here is a quote. Rules and figures were checked on 12 November 2026 against the sources listed at the end. Where we could not confirm a point from an official source, we say so in the text.
Last updated 12 November 2026. This piece sits in the Protect section.
The short answer
Use a formal channel: a bank or a regulated money-transfer provider. Compare the naira the recipient will actually receive, not the headline fee. Under Central Bank of Nigeria (CBN) rules, money-transfer operators pay recipients in naira only, and anything above the equivalent of US$200 must go into a bank account rather than be paid in cash. Check the provider is authorised (the FCA Register in the UK, the written disclosure before you pay in the US), and remember that a 1% US tax applies if you pay for the transfer in cash.
How big this corridor is
The World Bank reports that Nigeria received about US$22.79 billion in personal remittances in 2025, up from about US$22.13 billion in 2024. The series covers money sent from every country, not only the UK and US.
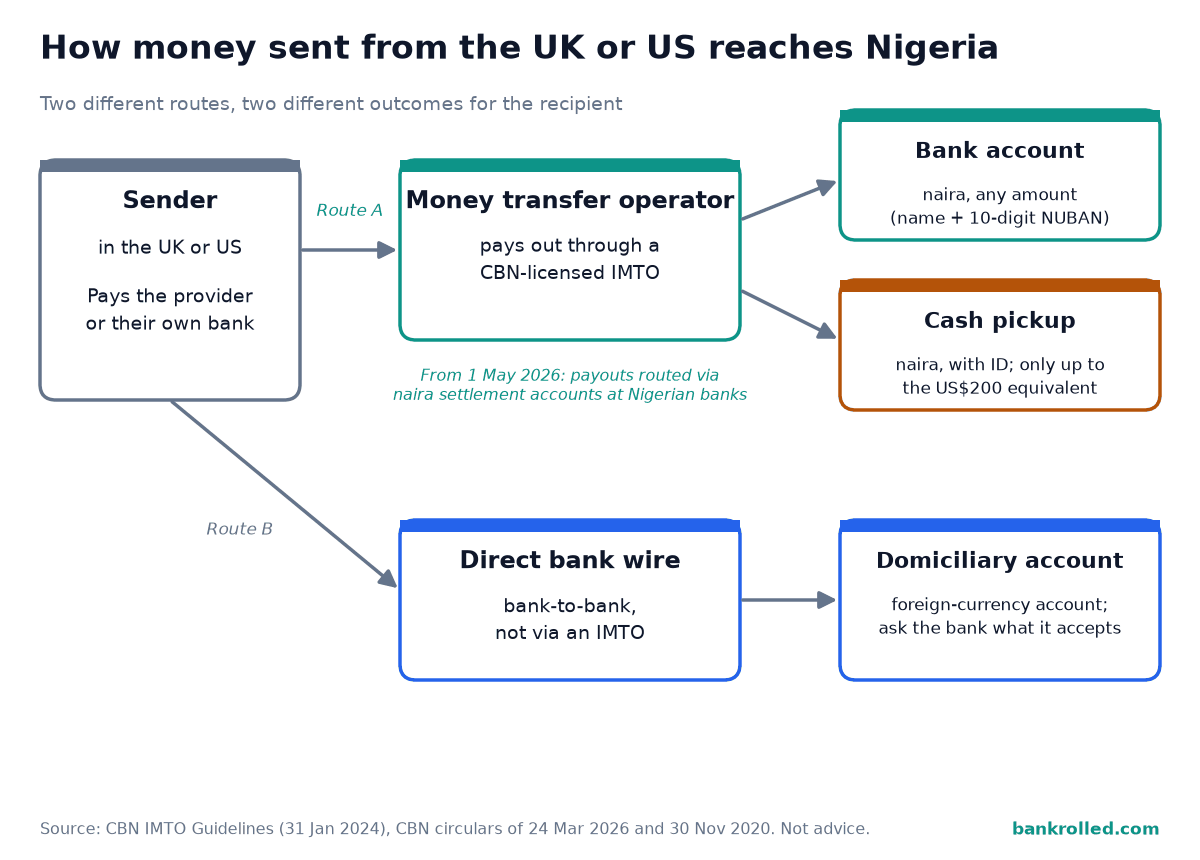
How the money can reach Nigeria
| Route | What the recipient needs | What to check before you send |
|---|---|---|
| Bank account deposit (naira) | The account name exactly as the bank holds it, the bank, and the account number (NUBAN) | That the name matches exactly; the money arrives in naira |
| Cash pickup (naira) | Acceptable ID and the transfer reference | That the amount is no more than the US$200 equivalent, the pickup point, and the ID it accepts |
| Mobile wallet or fintech account (such as OPay, PalmPay or Moniepoint) | A fully registered account in the recipient’s own name, at a KYC level that can take the amount | Whether your provider pays out to that wallet, the wallet’s KYC level and remaining room, and how the provider treats the payout under the US$200 rule; see the wallet section below |
| Direct bank wire to a domiciliary (foreign-currency) account | A domiciliary account and the bank’s international payment details | That the recipient’s bank accepts the currency and route, and what it charges |
The account number most Nigerians give you is the NUBAN, a CBN standard. The full NUBAN structure is 16 digits: an institution code, a 9-digit account serial number and a check digit. Our reading of the standard is that the number a customer sees is the serial plus the check digit, so 10 digits. Payout times depend on the provider and the route, so use the speed the provider shows you for your exact transfer.
Naira, not dollars
The CBN’s reviewed guidelines for international money transfer operators (IMTOs), dated 31 January 2024, say that all inbound money transfers to Nigeria “shall be paid to beneficiaries in Naira through a bank account, or cash”. Proceeds of more than the equivalent of US$200 must be paid through an account, and cash is paid only on acceptable identification. The exchange rate is “the prevailing rate in the Nigerian Foreign Exchange Market”, and an operator must use the rate on the day the transfer is received. So if a relative asks you to send dollars through a transfer app, the guidelines say they will receive naira.
Do not split a transfer to get under the cash limit. The same guidelines say an operator must not allow or process a transaction that appears to have been deliberately split into small amounts to avoid reporting requirements.
When a dollar (domiciliary) account is possible
A direct bank-to-bank wire is a different route from a money-transfer operator. A CBN circular of 30 November 2020 on domiciliary accounts says that where ordinary domiciliary accounts are “funded by electronic/wire transfer, account holders will be allowed unfettered and unrestricted use of these funds for eligible transactions”. Cash lodgements stay under the existing rules. That circular is from 2020 and we found no later CBN circular on domiciliary accounts when we checked, but rules can change, so the recipient should ask their own bank what it accepts and what it charges before you send. We did not check any Nigerian bank’s tariff, so we do not state receiving fees for wires.
Before you send to a Nigerian wallet
Wallets and fintech accounts such as OPay, PalmPay and Moniepoint are another way money can land in Nigeria. Each sets limits by know-your-customer (KYC) level, so a transfer can be declined, or the account restricted, if the recipient’s level is too low. Three checks come before you pay:
- The KYC level and remaining room. Ask the recipient to check their level and limits in the app.
- The exact legal name on the account. It should match what you give the provider.
- Whether your provider pays out to that wallet. Not every provider that sends to Nigeria does.
An open question: does a wallet count under the US$200 rule?
The CBN’s IMTO guidelines say inbound transfers are paid in naira “through a bank account, or cash”, and that proceeds of more than the equivalent of US$200 “shall be paid through an account”. The guidelines’ list of defined terms does not define “account”, and their payout section does not mention mobile wallets. The CBN’s 2021 mobile-money framework expects wallet operators to pass on “international inflow messages” to recipients by SMS, so it does foresee remittances reaching wallets. But we did not find a CBN page, or a wallet’s or provider’s page, that says whether a payout into a wallet counts as an account payout for the US$200 rule, when we checked on 12 November 2026. Before sending a larger amount to a wallet, ask the provider how it treats that payout. Do not split the amount to stay under the cash limit.
Which providers say they pay into Nigerian wallets
As one example, not a recommendation, WorldRemit’s Nigeria mobile-money page names OPay and Paga Money as wallets it can send to, in naira only, and says the account must be fully registered and active. The same page also says only PagaTech accounts are accepted and lists Paga’s own limits, so ask WorldRemit which wallets it currently pays into. We did not find a provider’s own page naming PalmPay or Moniepoint as a payout option. The Wise and Instarem UK pages we checked describe payouts to Nigerian bank accounts, so treat their quotes further down this page as quotes for a bank-account payout.
Moniepoint KYC limits
Moniepoint’s knowledge base lists three KYC levels for its personal and business accounts. These were the figures when we checked on 12 November 2026, in naira:
| KYC level | Single credit | Daily credit | Balance limit | Single debit | Daily debit |
|---|---|---|---|---|---|
| Level 1 | ₦50,000 | ₦300,000 | ₦300,000 | ₦50,000 | ₦300,000 |
| Level 2 | ₦100,000 | ₦500,000 | ₦500,000 | ₦100,000 | ₦500,000 |
| Level 3 | Unlimited | Unlimited | Unlimited | ₦5,000,000 | ₦5,000,000 |
Moniepoint says an account that goes over its level’s limits “will be automatically placed on restriction”, and that the restriction is lifted once documents for a higher level are uploaded and approved. A March 2024 Moniepoint blog post lists the documents: Level 1 needs BVN and liveness verification, a residential address and a signature; Level 2 adds next of kin, a verified government ID and proof of home address; Level 3 needs verified proof of home address and an indemnity.
PalmPay and OPay
PalmPay’s terms and conditions, last updated on 1 July 2026, list a daily transaction limit of ₦50,000 and a balance limit of ₦300,000 at Level 1, ₦200,000 and ₦500,000 at Level 2, which adds a BVN, and ₦5,000,000 with no balance limit at Level 3, which adds a photo ID and recent proof of address. PalmPay says transactions above a limit are declined, that it may lower limits as part of its risk controls, and that new accounts are limited to ₦20,000 a transaction, inflows included, for the first 24 hours. We could not open an official OPay page with its KYC limits on 12 November 2026, so we do not quote OPay figures; ask the recipient to check the OPay app.
The CBN’s ceilings for mobile-money wallets
Separately, the CBN’s Framework and Guidelines on Mobile Money Services in Nigeria (July 2021) set ceilings that wallet operators work within. They cover money going out of the wallet each day and the balance it can hold, not money coming in, so they are not the same as Moniepoint’s credit limits above:
| KYC level | Daily cumulative outflow | Cumulative balance limit |
|---|---|---|
| 1 | ₦50,000 | ₦300,000 |
| 2 | ₦200,000 | ₦500,000 |
| 3 | ₦5,000,000 | Unlimited |
The framework adds that the CBN “may determine the transaction limits from time to time”, so the app is the place to check the figure that applies today.
What changed on 1 May 2026
A CBN circular dated 24 March 2026, on measures to deepen diaspora remittances, took effect on 1 May 2026. It requires every IMTO to route its transactions, “including disbursements to beneficiaries”, through designated naira settlement accounts with authorised dealer banks in Nigeria. It also says IMTOs “shall observe real-time market prices from the Bloomberg BMATCH and utilise this as guidance for pricing transactions with their customers”.
For a sender, the practical point is that operators are expected to price against the official market. That does not mean every quote will be the same, and we do not predict where rates will go. It is one more reason to compare the naira received on the day you send.
Why formal channels matter
Informal channels and the parallel market move money outside regulated firms. They give you no complaint route, no refund right and no protection if the money disappears. The CBN guidelines give a formal transfer duties an informal one does not: the operator must disclose the exchange rate, commission, fees and any other charge; where conversion is offered, it must disclose all charges and the rate before the transfer starts or at the point of payment; and it must run a free complaints unit with a phone line and email, acknowledge complaints and respond within two weeks of receiving them.
In the UK, HMRC says money transfer businesses must register under the Money Laundering Regulations. We did not fetch an official Nigerian page on the legal status of informal channels, so we do not state what Nigerian law says about them. If a firm cannot show you a licence and a written receipt showing what will arrive, do not use it.
What it really costs
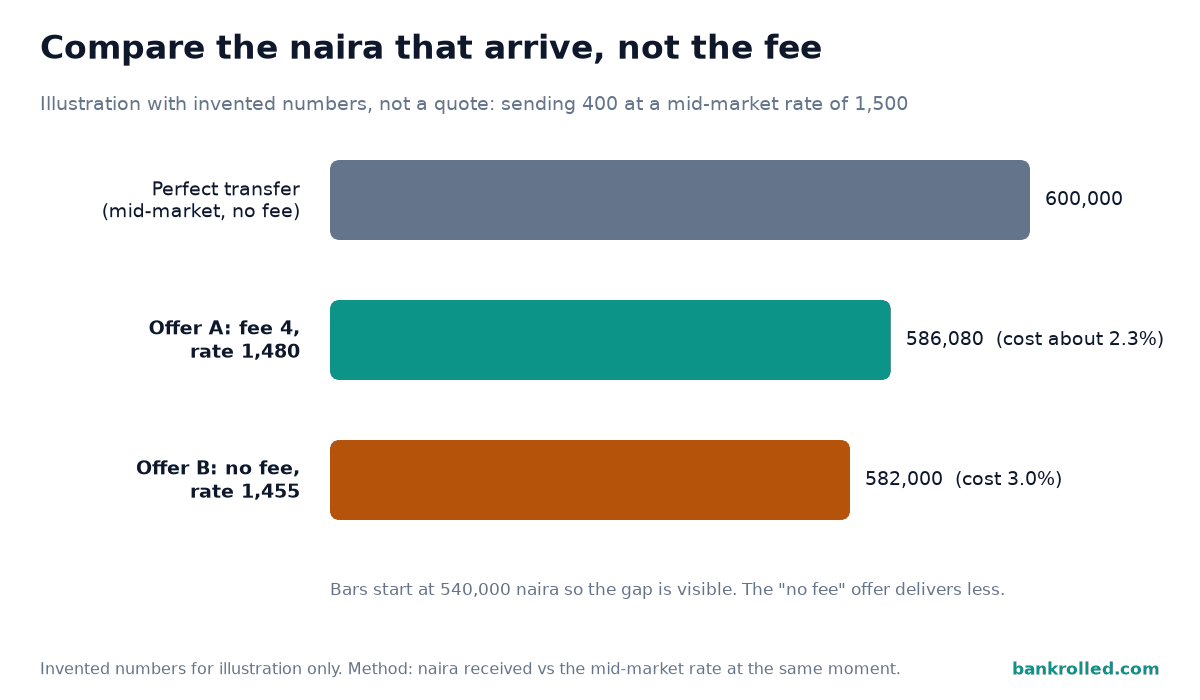
Fees are only part of the price. The exchange rate the provider uses is the other part. The mid-market rate is the rate banks use with each other, which you can see on a currency converter. The gap between that and the rate you are given is a cost.
The US Treasury quotes World Bank estimates in the Federal Register: for US$200 and US$500 remittance transfers sent from the United States in 2025, the average transaction fee was 5.56% and 3.81% of the amount, respectively. Those are global averages for sends from the US, not a price for Nigeria and not a quote.
To compare offers:
- Write down the exact number of naira the recipient will receive after all fees.
- Look up the mid-market rate at the same moment.
- Divide naira received by the mid-market rate. The difference from what you sent is your real cost.
Illustration (invented numbers, not a quote). You send 400. The mid-market rate is 1,500 naira per unit, so a perfect transfer delivers 600,000 naira. Offer A charges a fee of 4 and uses a rate of 1,480, so the recipient gets 396 × 1,480 = 586,080 naira, a cost of 13,920 naira or about 2.3%. Offer B has no fee but uses a rate of 1,455, so the recipient gets 582,000 naira, a cost of 18,000 naira or 3.0%. The “no fee” offer is the dearer one.
Bankrolled may earn a commission if you sign up through this link. It does not change the product or price.
Two quotes to compare. Wise and Instarem both list transfers from the UK to Nigeria (GBP to NGN) on their UK sites. Price the same amount with each on the same day, run the steps above on both, and keep the one that delivers more naira. This is not a ranking: Bankrolled has affiliate links with both, and other regulated providers may be cheaper for your amount. Price a transfer with Instarem, then check Wise below. In the UK, Instarem is a brand operated by Nium Fintech Limited, which the Financial Conduct Authority authorises to issue electronic money and provide payment services (reference 901024). That makes it an e-money firm, not a bank. Instarem’s other countries have other entities, so check the one that serves yours (UK pages checked 12 November 2026).
Sending from the UK: checks
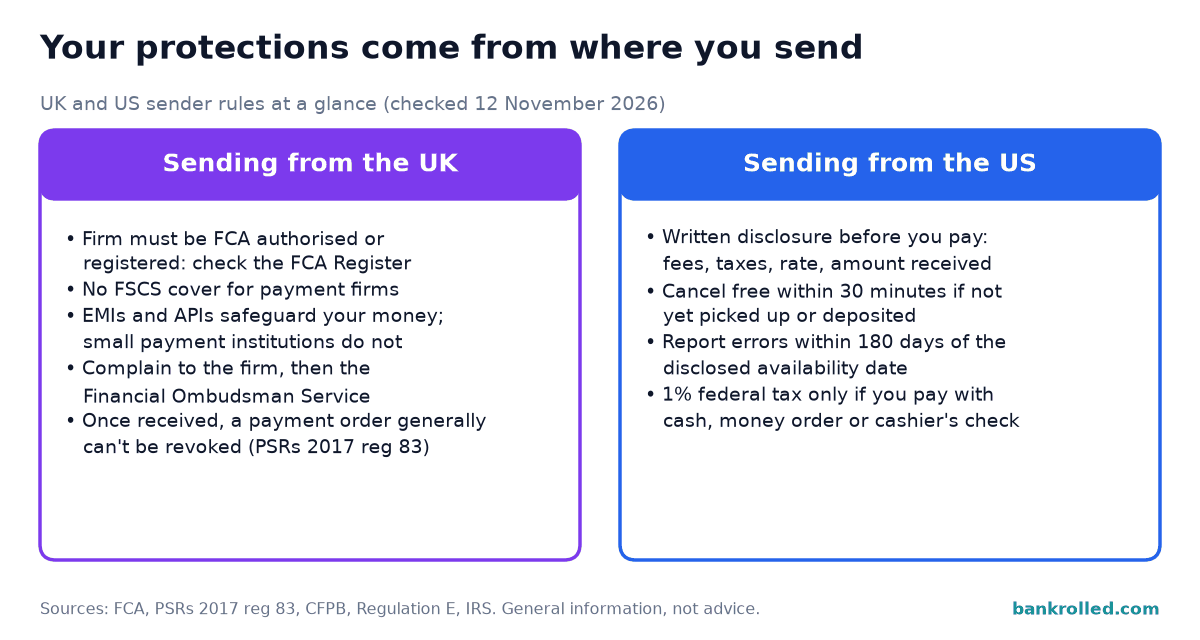
- Check the firm is authorised. The FCA says non-bank payment providers, such as authorised payment institutions, small payment institutions and electronic money institutions, must be authorised or registered. Search the FCA Financial Services Register by the provider’s legal company name.
- Know what is protected. The FCA says there is no Financial Services Compensation Scheme cover for these firms. Electronic money institutions and authorised payment institutions must safeguard customer money; small payment institutions do not have to.
- Complaints. Complain to the provider first. If you are unhappy with the answer, you can go to the Financial Ombudsman Service.
- Money transfer businesses must be registered with HMRC under the Money Laundering Regulations.
- Cancelling. Under regulation 83 of the Payment Services Regulations 2017, a payment order generally cannot be revoked once your provider has received it, unless you agree otherwise with the provider. Check the provider’s terms before you pay.
Sending from the US: checks and rights
The 1% remittance tax applies only to some payments
The IRS says that beginning 1 January 2026, a 1% remittance transfer tax applies to remittances sent from the United States when the sender provides cash, a money order, a cashier’s check or another similar physical instrument to the provider. The sender is liable for the tax and the provider collects it. On US$500 paid in cash the tax would be US$5.
These are still proposed regulations. Comments were due on 12 June 2026, and we found no final regulations when we checked on 12 November 2026. IRS Notice 2026-52 extends penalty relief for remittance transfer providers until final regulations apply.
What a US provider must show you
Under the CFPB’s remittance rule (Regulation E, subpart B), before you pay, the provider must show the amount transferred, its fees and any taxes, the total, the exchange rate, and the amount the recipient will get. Your receipt adds the date the money will be available, your error and cancellation rights, and contact details for the provider and regulators.
Cancelling and errors
- Cancel. The CFPB says you can cancel at no cost if the money has not been picked up or deposited, you paid less than 30 minutes ago, and you gave enough information for the provider to find the transfer. A scheduled transfer can be cancelled up to three business days before it is made.
- Errors. Tell the provider within 180 days of the date it disclosed the money would be available. It must investigate within 90 days of your notice and then report the result to you.
- Wrong account. If you gave an incorrect account number, the transfer may not count as an error under section 1005.33, so you could lose the money. Check the NUBAN twice.
Receiving in Nigeria: what the recipient may be asked
For cash pickup, the recipient needs acceptable ID, and under the CBN guidelines cash is only for amounts up to the US$200 equivalent. For a bank payout, the name you give should match the account exactly, and the account number should be the recipient’s NUBAN. Tell your recipient to keep the transfer reference and contact the operator if a payment is delayed. The CBN guidelines say agent contracts must prohibit charging the beneficiary any fees other than those agreed with the sender when the transfer started, so a recipient asked for an extra fee at a payout point should ask why and keep a record.
If you are a freelancer in Nigeria paid from the UK or US
If you live in Nigeria and clients abroad pay you, see our guides to getting paid in one country while you live in another, the payout fee stack on a US$2,000 payment, why a USD payment can arrive short and the W-8BEN. For tax residence, see tax residence versus where your client is, and for money held across borders, moving money across borders without a UK bank.
Safe-sending checklist
- Is the company on the FCA Register (UK), or does it give the US disclosure before you pay?
- Does the quote show the exact naira the recipient will receive?
- Is the amount for cash pickup within the US$200 equivalent? If not, use a bank account, and do not split the transfer.
- Does the recipient’s name match their bank account exactly, and have you checked the 10-digit account number?
- If the money is going to a wallet, has the recipient confirmed their KYC level and limits, and has the provider told you how it treats the payout under the US$200 rule?
- Did you pay in a way that avoids the 1% US tax, where that applies?
- If the recipient wants dollars, have they asked their bank whether their domiciliary account can take a wire?
- Did someone ask you to pay into new bank details? Check using our guide on checking a change of bank details before you pay.
- Have you kept the receipt and reference number?
If a bank closes your account because you live abroad, see what to do when a bank closes your account. For where to keep emergency money, see deposit protection abroad and emergency cash when ISAs and the FSCS do not apply. Other corridors: India, Pakistan and the Philippines.
Frequently asked questions
What is the cheapest way to send money to Nigeria from the UK or US?
There is no single answer: it depends on the amount, the payout method and the rate on the day. Compare the naira the recipient receives for each offer against the mid-market rate at the same moment. A low fee with a poor rate can cost more than a higher fee with a good rate.
Can my recipient get dollars, or only naira?
Through a money-transfer operator, naira only: the CBN guidelines say inbound transfers are paid to beneficiaries in naira. A direct bank wire into a domiciliary (foreign-currency) account is a different route, covered by a 2020 CBN circular. The recipient should ask their bank what it accepts.
Is there a limit on cash pickup in Nigeria?
Yes. Under the CBN guidelines, money-transfer proceeds of more than the equivalent of US$200 must be paid through an account, and cash is paid only on acceptable identification.
Can I send money to an OPay, PalmPay or Moniepoint account from the UK or US?
Some providers say they pay into Nigerian wallets; WorldRemit’s Nigeria page, for example, names OPay. Check that the provider pays into the recipient’s wallet, and ask the recipient to confirm their KYC level and limits first. Moniepoint, for example, restricts an account that goes over its level’s limits until it is upgraded.
Does the US$200 cash limit apply to wallet payouts?
We could not confirm this. CBN rules say transfers above the US$200 equivalent must be paid through an account, but we did not find an official page that says whether a wallet payout counts as one. Ask your provider how it treats the payout, and do not split a transfer to stay under the limit.
What details does the recipient need?
For a bank payout: their name exactly as on the account, the bank, and the account number (NUBAN). For cash pickup: acceptable ID and the transfer reference.
What changed on 1 May 2026?
A CBN circular of 24 March 2026 requires money-transfer operators to route transactions, including payouts, through naira settlement accounts at authorised dealer banks, and to use Bloomberg BMATCH real-time prices as guidance for pricing.
Can the recipient be charged a fee at the Nigerian end?
Under the CBN guidelines, an operator’s agents must not charge the beneficiary any fees other than those agreed with the sender at the start. Fees a Nigerian bank charges on a direct wire are a separate matter; we did not check bank tariffs, so ask the bank.
Is there a US tax on sending money to Nigeria?
A 1% federal tax applies only when you fund the transfer with cash, a money order, a cashier’s check or a similar physical instrument. The sender is liable. The regulations were still proposed when we checked.
Can I cancel or fix a transfer that went wrong?
In the US, you can cancel at no cost within 30 minutes of paying if the money has not been picked up or deposited, and you have 180 days to report an error. In the UK, regulation 83 of the Payment Services Regulations 2017 says a payment order generally cannot be revoked once your provider has received it; complain to the provider and then the Financial Ombudsman Service.
Can I pay with a credit card or PayPal?
The provider decides which payment methods it accepts, and the quote should show the total you pay. If you pay by credit card, your card issuer may add its own charges, so check your card terms. We did not check any card issuer’s fees.
How do I check a provider is legitimate?
In the UK, search the FCA Register. In the US, you should get the written disclosure before you pay. Ask which licensed Nigerian partner pays out. The CBN publishes a list of licensed IMTOs, but the latest one on its site when we checked is dated 31 August 2023, so it may be out of date.
What this guide does not cover
It is not tax, legal or financial advice. We have not listed named providers’ fees, speeds or limits, because they change often and we did not check any provider’s fee page for this edition; the method above shows how to compare live quotes. We did not check mobile wallet rules, bank wire charges or any reward schemes. We do not cover sending money out of Nigeria, Nigerian tax on money received, buying property in Nigeria, crypto, or business payments.
Sources
- World Bank: Personal remittances, received (current US$), Nigeria, checked 12 November 2026
- Central Bank of Nigeria: Reviewed Guidelines of International Money Transfer Services in Nigeria (TED/FEM/FPC/GEN/001/002), 31 January 2024, checked 12 November 2026
- Central Bank of Nigeria: Measures to Further Deepen Diaspora Remittances and Compliance (TED/FEM/FPC/PUB/001/002), 24 March 2026, checked 12 November 2026
- Central Bank of Nigeria: Operations of Domiciliary Accounts (TED/FEM/FPC/GEN/01/010), 30 November 2020, checked 12 November 2026
- Central Bank of Nigeria: Revised Standards on Nigeria Uniform Bank Account Number (NUBAN), checked 12 November 2026
- Central Bank of Nigeria: Updated List of IMTOs as at 31 August 2023, checked 12 November 2026
- Central Bank of Nigeria: Framework and Guidelines on Mobile Money Services in Nigeria, July 2021, checked 12 November 2026
- Moniepoint knowledge base: transaction limits for each KYC level, checked 12 November 2026
- Moniepoint blog: We’re updating our banking account tiers, 17 March 2024, checked 12 November 2026
- PalmPay: terms and conditions, last updated 1 July 2026, checked 12 November 2026
- WorldRemit: Send mobile money to Nigeria, checked 12 November 2026
- IRS: Treasury, IRS issue proposed regulations on the new remittance transfer tax, checked 12 November 2026
- IRS Notice 2026-52, extending penalty relief for remittance transfer providers, checked 12 November 2026
- Federal Register: Excise Tax on Remittance Transfers, 13 April 2026, checked 12 November 2026
- CFPB: Can I cancel an international money transfer?, last reviewed 3 October 2024, checked 12 November 2026
- CFPB: Regulation E section 1005.31, disclosures, checked 12 November 2026
- CFPB: Regulation E section 1005.33, procedures for resolving errors, checked 12 November 2026
- FCA: Using payment service providers, page last updated 8 January 2026, checked 12 November 2026
- FCA Financial Services Register, checked 12 November 2026
- legislation.gov.uk: Payment Services Regulations 2017, regulation 83 (revocation of a payment order), checked 12 November 2026
- GOV.UK: Money laundering regulations, who needs to register, checked 12 November 2026
- Financial Ombudsman Service, checked 12 November 2026
- Instarem UK: Send money to Nigeria (GBP to NGN; FCA authorisation notice for Nium Fintech Limited, reference 901024), checked 12 November 2026
- Wise UK: Send money to Nigeria (GBP to NGN), checked 12 November 2026
Still got a question? Ask Bankrolled and get a quick answer from our guides.
